Buying a car is a big decision, but knowing how much you can actually afford makes the process less stressful. Many people jump into car shopping with only a rough idea of their budget, then find themselves stretched thin by monthly payments, surprise costs, or expensive insurance.
If you want to avoid these problems and drive away with confidence, you need a clear plan for what you can really spend on your next car.
Let’s walk through everything you need to know to answer the important question: How much car can I afford? You’ll learn how to set a smart budget, avoid common mistakes, and make choices that keep your finances healthy—now and in the future.
Understanding Your Car Budget
Before visiting dealerships or browsing online, get a full picture of your finances. Don’t just ask, “How much down payment do I have?” Instead, look at your monthly income, expenses, savings, and any debts.
1. Know Your Monthly Income
Add up your take-home pay after taxes. If your income changes each month, use an average from the past six months.
2. List All Monthly Expenses
This includes rent or mortgage, food, utilities, insurance, credit card payments, and other regular bills. Don’t forget savings and emergency fund contributions.
3. Subtract Expenses From Income
What’s left is your “discretionary income”—the money you can use for things like a car payment.
4. Set A Safe Limit
Experts often recommend that your car payment plus car costs (like fuel and insurance) should not be more than 15% of your take-home pay. If you want to be extra safe, keep it to 10%.
For example, if you bring home $3,500 per month, 10% is $350 and 15% is $525. This is your maximum for all car costs, not just the loan.
The 20/4/10 Rule Explained
There’s a simple guideline to help you decide how much car you can afford: the 20/4/10 Rule.
- 20% down payment: Try to pay at least 20% of the car’s price upfront.
- 4 years loan maximum: Don’t finance for more than 4 years.
- 10% of monthly income: Keep all car expenses under 10% of your take-home pay.
Why does this rule work? It protects you from high-interest costs, negative equity (owing more than the car is worth), and surprise budget problems.
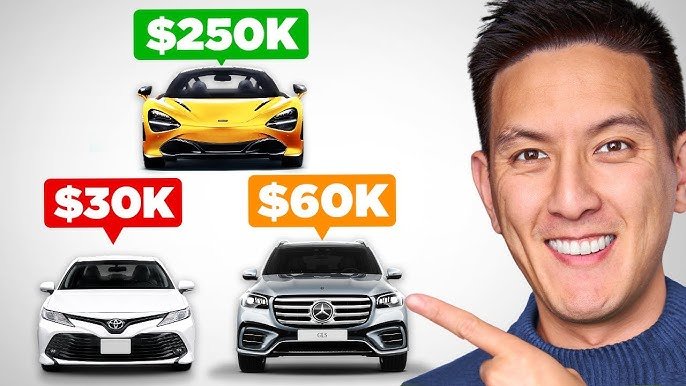
Many buyers ignore the “4 years” part and stretch loans to 6 or 7 years. This lowers payments but means you pay much more interest—and risk being “upside down” on your loan.
Credit: www.youtube.com
Key Factors That Affect Car Affordability
Choosing a car is not just about the sticker price. Several important factors can change what you really pay.
1. Interest Rates
Your credit score affects the rate lenders offer. A higher score means lower interest costs. For example, someone with excellent credit might get 3% APR, while someone with poor credit could pay 10% or more.
2. Loan Term
A longer loan term lowers monthly payments but increases the total interest you pay. A 72-month loan looks cheaper each month but is more expensive overall.
3. Insurance Costs
Car insurance can vary a lot depending on the car’s age, type, and your driving history. A new sports car might cost twice as much to insure as a used sedan.
4. Taxes And Fees
When you buy, you’ll pay sales tax, title, and registration fees. These can add 8–10% or more to the car’s price.
5. Maintenance And Repairs
A used car may need more repairs, while a new car has warranty coverage but loses value faster. Don’t forget regular costs like oil changes, tires, and brake pads.
6. Fuel Economy
Fuel costs can add up. A car that gets 40 miles per gallon saves money compared to a truck that gets 15 mpg, especially if you drive a lot.
How To Calculate Your Affordable Car Price
Let’s put the above ideas into action with a step-by-step example:
Suppose your monthly take-home pay is $4,000. You want to follow the 20/4/10 rule and have $6,000 saved for a down payment.
1. Monthly Car Costs Limit: 10% Of $4,000 = $400
This includes loan payment, insurance, fuel, and maintenance.
- Estimate Non-Loan Costs:
- Insurance: $90/month
- Fuel: $80/month
- Maintenance: $30/month
Total: $200/month
3. Monthly Loan Payment Left:
$400 – $200 = $200/month For Loan Payment
- Down Payment: $6,000 (aim for 20% of car price)
- Find Total Car Price:
If $6,000 is 20%, total car price = $6,000 ÷ 0. 2 = $30,000
- Loan Amount Needed: $30,000 – $6,000 = $24,000
- Loan Calculator:
For a 4-year loan at 5% APR, $24,000 financed = about $552/month—too high for our $200/month target.
8. Adjust Price:
To keep the loan payment at $200/month for 4 years at 5% APR, you could afford to borrow about $8,700. Add your $6,000 down payment = $14,700 car price.
This example shows why you must check the numbers carefully, not just guess.
New Car Vs Used Car: Which Is More Affordable?
You might wonder if a new car or used car fits your budget better. Each has pros and cons.
| Feature | New Car | Used Car |
|---|---|---|
| Price | More expensive | Cheaper upfront |
| Depreciation | Loses value quickly | Slower value loss |
| Warranty | Full coverage | May have some left |
| Repair Costs | Low (at first) | Can be higher |
| Interest Rates | Lower | Can be higher |
Non-obvious insight: Many buyers forget that a new car loses 20–30% of its value in the first year. That means a $30,000 car may be worth only $21,000 after 12 months—even if it’s still in great shape.
Leasing Vs Buying
Not everyone buys their car—some choose to lease. Leasing means paying for the right to drive a car for a set time, usually 2–3 years, then returning it.
| Factor | Leasing | Buying |
|---|---|---|
| Monthly Payment | Usually lower | Usually higher |
| Ownership | No | Yes |
| Mileage Limits | Strict | None |
| Customization | Not allowed | Allowed |
| Total Cost | Higher long-term | Lower long-term |
Leasing can be tempting because of lower payments, but you never own the car, and there are often strict rules about mileage and wear.
Credit: www.ramseysolutions.com
Don’t Forget About Total Cost Of Ownership
Many people focus only on the price tag or monthly payment. The smarter approach is to consider the total cost of ownership. This includes:
- Depreciation
- Interest
- Taxes & fees
- Insurance
- Fuel
- Maintenance & repairs
For example, a cheap older car may need expensive repairs. A new hybrid may cost more upfront, but save money on fuel and maintenance.
Here’s a simple comparison:
| Car Type | Purchase Price | 5-Year Total Cost |
|---|---|---|
| Used Sedan | $12,000 | $25,000 |
| New SUV | $35,000 | $55,000 |
| Hybrid Compact | $20,000 | $28,000 |
Non-obvious insight: The cheapest car to buy is not always the cheapest to own. Gas, maintenance, and insurance can add up quickly.
Common Mistakes When Budgeting For A Car
Many buyers make the same errors. Avoid these to protect your finances:
1. Focusing Only On Monthly Payment
A low payment often means a longer loan and more interest.
2. Ignoring Extra Costs
Taxes, fees, insurance, and maintenance add up.
3. Not Saving Enough For A Down Payment
A small down payment means bigger loans and higher payments.
4. Overestimating Trade-in Value
Dealers may offer less than you expect for your old car.
5. Skipping The Pre-approval Step
Shop for financing before you shop for the car to get better rates.
6. Not Researching Insurance
Some cars cost much more to insure.
7. Buying More Car Than You Need
It’s easy to be tempted by bigger, fancier cars. Stick to your real needs.
How To Get The Best Deal For Your Budget
You don’t always have to pay the sticker price. Here’s how to stretch your budget further:
1. Shop For Financing First
Credit unions and online lenders often offer better rates than dealers.
2. Consider Certified Pre-owned (cpo) Cars
These are used cars with warranties and inspections—often a good balance of price and peace of mind.
3. Look For Rebates And Incentives
Manufacturers sometimes offer cash back or low-interest loans.
4. Negotiate The Price, Not The Payment
Dealers can hide costs in a low monthly payment.
5. Be Patient
The right deal takes time. Don’t rush the process.
6. Check Insurance Quotes Before Buying
Surprise insurance costs can wreck your budget.
Practical Example: Finding Your Car Budget
Let’s follow the journey of Sam, a teacher with a take-home pay of $3,200 per month.
- He has $5,000 saved for a down payment.
- His regular expenses (rent, food, etc.) Leave him with $500 per month for a car.
- Insurance for his favorite car model is $110/month.
- He drives 800 miles per month; fuel costs $100/month.
- Maintenance averages $30/month.
So, his total car costs (insurance, fuel, maintenance) = $240/month.
That leaves $260/month for a loan payment.
He uses a car loan calculator and finds that, with a $5,000 down payment and $260/month for 4 years at 6% interest, he can afford a car around $16,500.
He shops for reliable used sedans in this price range, checks insurance before buying, and avoids cars that need expensive repairs. Sam stays within his budget and avoids financial stress.
Credit: www.ramseysolutions.com
Frequently Asked Questions
How Much Should I Spend On A Car If I Have Debt?
If you have debt, it’s wise to be extra careful. Try to keep your total car costs below 10% of your take-home pay. If your monthly budget is tight, consider a reliable used car and save for a larger down payment. Avoid long loan terms—focus on reducing debt first.
Is It Better To Buy Or Lease If I Want A Lower Payment?
Leasing often gives you a lower monthly payment, but you never own the car and may face extra fees for mileage or wear. Buying lets you build equity and eventually drive payment-free. If your budget is tight, a used car purchase is usually more affordable in the long run.
What Credit Score Do I Need To Get A Good Car Loan?
A credit score of 700 or higher usually gets the best rates. You can still get a loan with a lower score, but you’ll pay more in interest. Before applying, check your credit report and fix any errors. Learn more about credit and car loans at Consumer Financial Protection Bureau.
How Much Should I Save For A Down Payment?
Aim for at least 20% of the car’s price. A larger down payment means a smaller loan, lower monthly payments, and less interest over time. If you can’t reach 20%, try for at least 10% to avoid being “upside down” on your loan.
Should I Get Pre-approved Before Shopping For A Car?
Yes, getting pre-approved for a loan lets you know your budget, makes negotiations easier, and often gets you a better interest rate. It also helps you avoid last-minute surprises at the dealership.
Car shopping is exciting, but smart planning makes it rewarding, too. By understanding your real budget, including all the hidden costs, and following tried-and-true rules, you can drive home the right car—without regrets or financial stress.